After a failed launch, how do entrepreneurs deal with failure without risking the business that still serves customers? You contain the damage, review the evidence, protect relationships, and choose whether to repair, pivot, or close. Persistence is not always the responsible response.
Postmortem analysis means a structured review of events, their causes, and needed changes before your next decision. A setback earns its value through better decisions, not through the fact that you survived it. The aim is a choice you can explain and fund.
A failed initiative differs from a business that cannot meet its commitments. In Singapore, your customers may await delivery while employees expect pay and partners depend on agreed work. Cash flow management protects those commitments while you assess the damage.
Resilience under uncertainty starts with seeing those competing claims clearly. You need enough perspective to judge them without making disappointment your decision-maker.
How Do Entrepreneurs Deal With Failure Without Losing Perspective?
You lose an important customer and reach for your phone to send an angry message. Put the message aside before sending, unless an urgent customer or operational problem needs immediate containment. A brief pause can separate a necessary response from an impulsive one.
Take responsibility for your decision without treating business performance as your personal worth. Founder resilience means keeping that distinction clear enough to act. Disappointment can remain present without directing every conversation.
Speak privately with someone you trust, such as a friend, family member, mentor, or peer. Explain what happened before asking for advice. That conversation can reduce isolation without turning your listener into the person responsible for your next choice.
Write two short statements: what happened, and what you fear it means. “The customer canceled” describes an event; “nobody will buy again” expresses a fear. Keep the second statement out of decisions until evidence supports it.
When you ask “how do entrepreneurs deal with failure,” start with the decisions that need attention today. Sleep, time away, and delegated decisions can support sound judgment. They are practical safeguards, not rewards you must earn through more work.
Founder burnout deserves attention rather than another demand to push harder. Seek professional support if distress persists or disrupts daily functioning. With some perspective restored, ask what needs protection first.
Protect Cash and Keep Stakeholders Informed
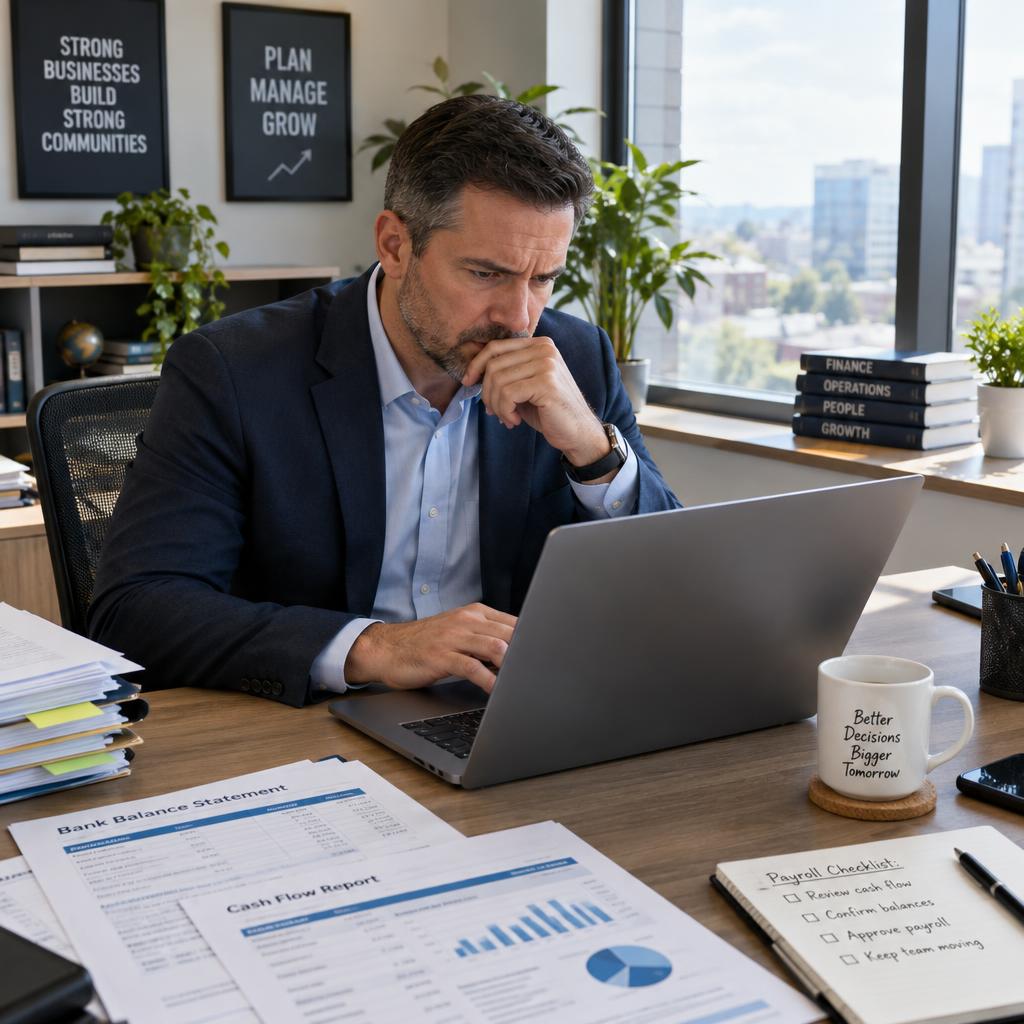
A healthy sales pipeline can coexist with too little money for the next payment cycle. Protecting your options starts with knowing what you can actually pay, not what you hope to sell. Revenue alone does not show whether you can meet commitments.
Stakeholders are the people affected by your business decisions, including customers, employees, suppliers, and partners. Their needs differ, but each needs facts they can use. Financial risk management starts with an accurate position and clear communication, rather than an upbeat forecast.
Establish What the Business Can Still Afford
Available cash means cash available for operating commitments. Separate money you can access now from expected receipts, even when customers have promised payment. Match confirmed payment timing against essential commitments and avoidable future spending.
- Reconcile accessible bank balances.
- Date expected customer receipts.
- Date payroll, supplier, rent, and debt commitments.
- Identify discretionary commitments that can still be paused.
A signed contract does not place money in your bank account. Cash flow management needs actual collection dates alongside planned payments. Mark uncertain receipts clearly instead of using them to cover a gap on paper.
Give People Facts They Can Act On
Tailor updates to each audience, covering known impact, immediate action, unresolved questions, and the next update. Rebuilding stakeholder trust starts with useful facts, not reassurance alone. Distinguish what you know from what you are still checking.
Consider a hypothetical Singapore service business facing a delayed delivery. Customers need practical choices about timing or a reduced scope; employees need clarity about work and pay. Partners may need revised handover plans to avoid disrupting their own customers.
Do not promise a refund or recovery date before checking whether you can deliver it. Record promises so your team does not give conflicting answers. Once immediate exposure is visible, examine the evidence explaining how it arose.
Find the Cause Before Choosing the Fix
“Customers did not buy” describes an outcome, not a cause. A postmortem analysis compares your original assumption with actual results, then tests possible explanations. Choose a correction only after evidence supports the diagnosis.
Write down what you expected customers to do and what they actually did. Examine customer conversations, buying behavior, delivery records, and financial records together. Customer feedback analysis works best when comments connect to actions, such as buying, canceling, returning, or renewing.
These are diagnostic possibilities, not findings about your business. Use the evidence column to test each possibility before committing to a correction. Several causes may overlap, so avoid forcing every record into one neat explanation.
References carry more weight when they come from people who worked directly with the candidate. Investment in an offering cannot replace evidence of a clear customer need. Both checks turn learning from business setbacks into specific changes.
Do not treat the loudest complaint as the voice of every customer. Compare that complaint with other accounts and buying patterns. Ask what you controlled and what changed outside the business, without assuming every external explanation is an excuse.
Lessons from failed ventures also require an honest look at your own habits. Comparing the four entrepreneur types can help you question strengths that may also create blind spots. End the review with a documented change, a named owner, and a way to check its effect.
Use that diagnosis to choose a recovery path, rather than defaulting to another attempt.
Repair, Pivot, or Close: Choose on Evidence
What has changed besides your willingness to try again? Choose repair, a business model pivot, or closure based on present evidence, remaining resources, and obligations. Time and money already spent cannot justify continuing an unviable course.
Your next choice must stand without the need to prove earlier decisions right. Protecting people and preserving cash can matter more than keeping an offer alive. Judge the path by what it can support now, not by how painful it feels to abandon past work.
Repair or Pivot When Demand Still Has Support
Repair changes execution when customers still value the offer. A business model pivot materially changes how the business creates and earns value. Pivoting a business model can mean changing the customer segment, offer, route to market, or revenue model.
Consider a hypothetical Singapore service firm with repeat purchases but frequent delivery complaints. Those purchases support demand, while the complaints suggest an execution problem. Interest without willingness to pay raises a different question about the offer or revenue model.
- Does observable customer behavior support demand?
- Can the next change be funded without depending on uncertain receipts?
- What new evidence makes this attempt different from the last?
Business model pivots need evidence beyond a fresh pitch or new branding. A customer who praises an idea has not made the same commitment as one who pays. Keep that difference visible when assessing post-failure recovery.
Close Responsibly When Another Attempt Cannot Be Justified
Closure can be responsible when you lack credible demand, an affordable test, or a workable way to address unresolved obligations. Closing an initiative differs from closing the legal business entity. You may stop one service while continuing other work the business can support.
Startup exit strategies can include a sale, transfer, or wind-down, but each needs a realistic assessment of feasibility. Do not assume a buyer exists or that a transfer removes obligations. Seek qualified professional advice where solvency or formal closure is involved.
A responsible exit protects people from promises the business cannot keep. For founders continuing or restarting, shift attention from the size of your ambition to controls on the next commitment.
Make the Next Risk Smaller and Easier to Read
Replace a full rollout with a paid pilot for one revised service. A bounded test lets you seek evidence without committing the whole business. Set the exposure boundary and review trigger before spending begins.
A short pre-mortem asks how a future initiative could fail before you commit resources fully. Acceptable loss sets boundaries on the cash, time, and customer impact you are willing to risk. Agree which warning signs require a review rather than leaving that choice to a pressured team.
Use these examples as a practical test template, not as reported results. Replace each boundary with a limit your business can support. A cash limit alone is incomplete if the test could also disrupt promised customer work.
Customer feedback loops become useful when feedback changes a decision or prompts a measurable test. The entrepreneur lifecycle framework connects execution and learning with the next round of discovery. Use that cycle to revise an assumption, not simply repeat an activity.
Ask a trusted peer to challenge your assumption and name evidence that would change your mind. Their questions can expose gaps, but advice does not guarantee a better result. Calculated risk-taking still leaves you responsible for the commitment.
Highly cautious teams may need a small, reversible test instead of an exhaustive list of threats. Financial risk management should make a sensible test possible, not make every test feel forbidden. A clear stopping rule gives you room to make the next decision calmly.
Choose One Decision You Can Defend
The strongest response may be a smaller commitment rather than a louder comeback. A defensible decision matters more than appearing relentlessly optimistic. Stopping an initiative can fit responsible entrepreneurship when continuing would expose others to harm you cannot justify.
Founder resilience includes the ability to change your judgment when evidence changes. Post-failure recovery need not look impressive from outside the business. It needs a choice you can explain to those who bear its consequences.
Schedule a focused conversation with a trusted peer. Bring a one-page decision note containing your choice, supporting evidence, and review trigger. Use that note to make the conversation about the decision, not the comeback.